ASU 2026-02 (Topic 818): Environmental Credits Accounting Guide for 2026
The FASB issued ASU 2026-02 on May 19, 2026, and it fills a gap that has existed in US GAAP for decades. For the first time, companies have authoritative guidance on how to recognize, measure, present, and disclose environmental credits and the regulatory compliance obligations that can be settled with them.
This guide is for CFOs, controllers, ESG finance teams, and technical accountants at any entity that buys carbon offsets, holds RECs, participates in cap-and-trade programs, or carries renewable fuel standard (RFS) obligations. If that describes your organization, ASU 2026-02 will change your balance sheet, your P&L, and your footnotes.
Key takeaway: ASU 2026-02 creates ASC Topic 818, the first comprehensive US GAAP model for environmental credits. Whether you capitalize or expense a credit now depends entirely on what you intend to do with it.
What Is ASU 2026-02 and Why Does It Matter?
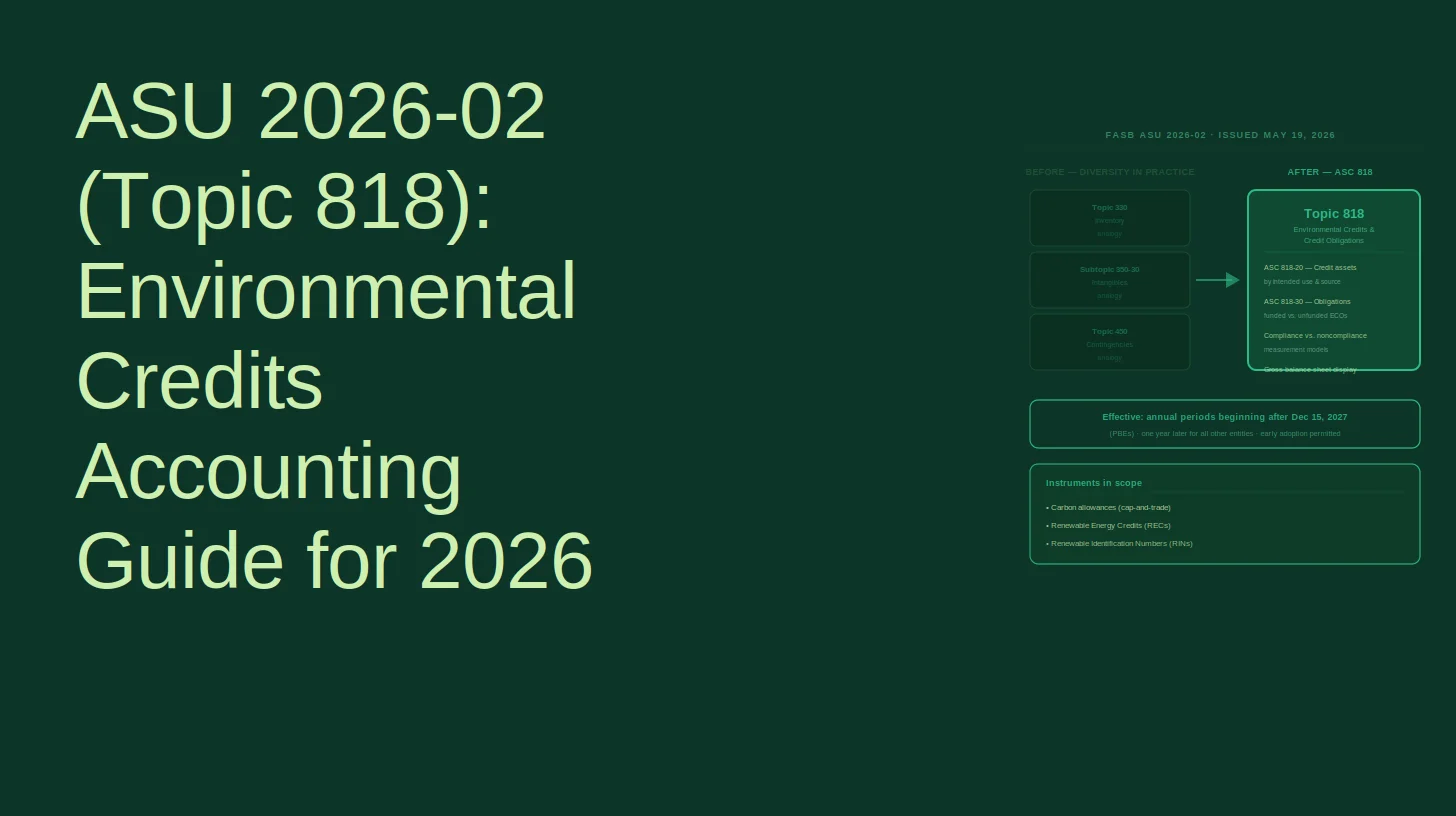
ASU 2026-02, formally titled "Environmental Credits and Environmental Credit Obligations (Topic 818)," establishes the first authoritative US GAAP framework for these instruments. Before this standard, no specific codified guidance existed. Teams applied analogies: some expensed credits immediately, others capitalized them under ASC 330 (Inventory) or ASC 350-30 (Intangibles), producing significant and unresolvable diversity in practice.
The obligation side ran on analogy too, mostly to ASC 450 (Contingencies) (ASU 2026-02, BC5). The gap is old. The EITF took up cap-and-trade allowances in Issue 03-14 in 2003 without reaching a consensus, and later FASB and IASB emissions projects came off both boards' agendas (BC3).
FASB added the current project in May 2022 after its 2021 agenda consultation. It exposed a proposal on December 17, 2024 and received 41 comment letters (BC8 and BC10).
The FASB's own news release puts it plainly: "The new ASU adds guidance that will provide clarity around accounting and disclosures that previously did not exist in environmental credits and related credit obligations."
For companies with active sustainability programs, the stakes are real. The accounting directly affects:
- Balance sheet size (gross presentation required; no netting permitted)
- P&L timing (voluntary/net-zero credits are expensed immediately)
- EPS (retained earnings adjustment at transition)
- Footnote disclosures (new, detailed annual requirements)
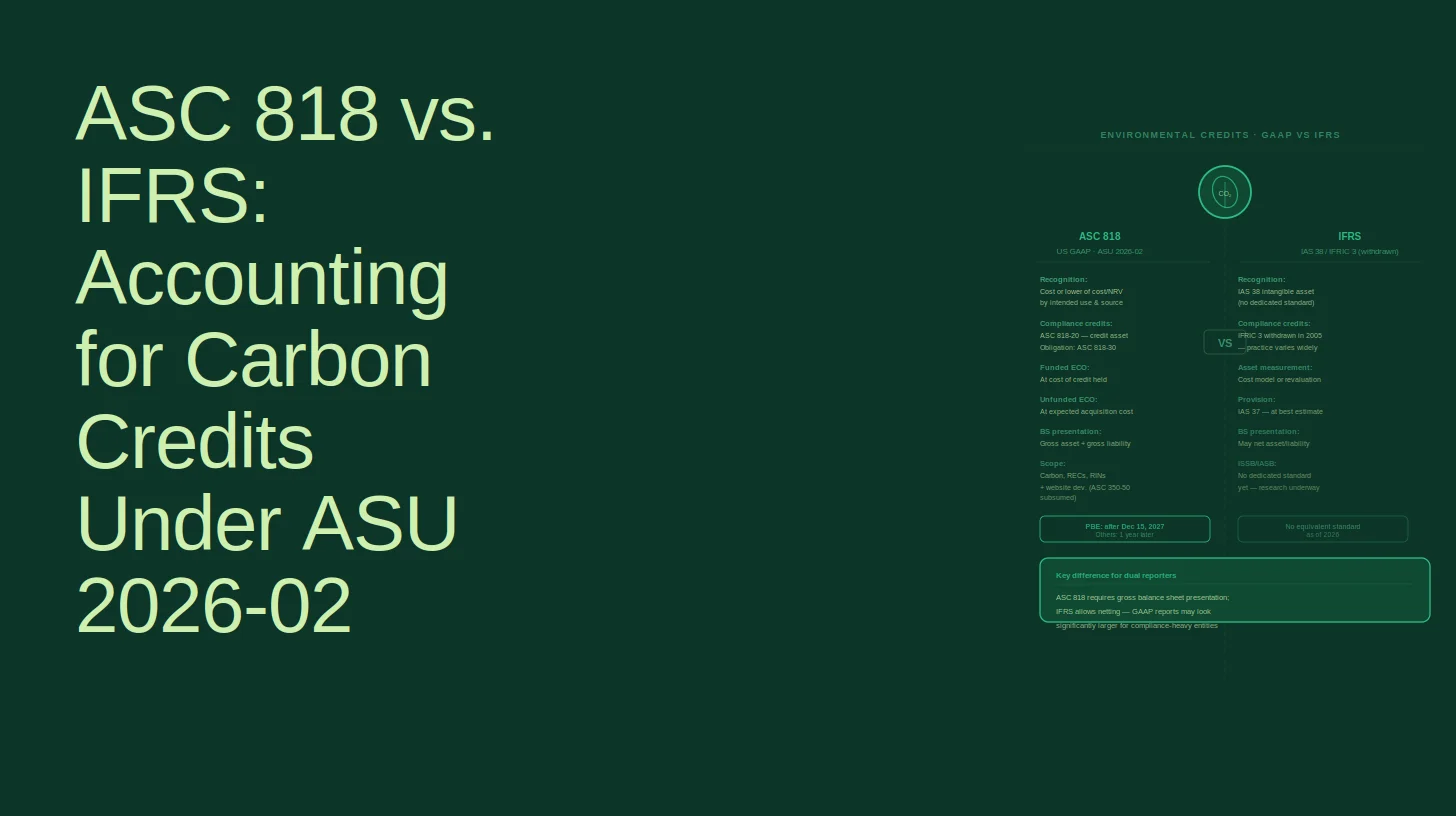
For how the same credits are treated under IFRS, see Finrep's ASC 818 vs IFRS comparison.
What Qualifies as an Environmental Credit Under Topic 818?
An environmental credit is an enforceable right that meets all four of the following criteria, per EY's AccountingLink analysis of the standard:
- It lacks physical substance and is not a financial asset.
- It is represented to prevent, control, reduce, or remove emissions or other pollution.
- It is, or previously was, separately transferable in an exchange transaction. (If no longer transferable, the entity must be able to use it to settle an ECO.)
- It is not an income tax credit that may be used to settle an entity's income tax liability.
Instruments that generally meet this definition include:
- Carbon offsets
- Renewable energy certificates (RECs)
- Cap-and-trade allowances and emission allowances
- Renewable identification numbers (RINs)
- Other industry-specific credits (e.g., credits under California's Low Carbon Fuel Standard)
One nuanced scoping point worth flagging: credits that have lost their separate transferability can still qualify if they can be used to settle an ECO. This matters for legacy or retired credits that an entity may still hold.
What Is an Environmental Credit Obligation (ECO)?
An ECO is a regulatory compliance obligation arising from existing or enacted laws, statutes, or ordinances represented to prevent, control, reduce, or remove emissions or other pollution, where the obligation may be settled with environmental credits. The FASB's Basis for Conclusions (paragraph BC6) confirms this definition captures cap-and-trade programs, renewable portfolio standard (RPS) programs, and renewable fuel standard (RFS) programs.
Two important exclusions:
- Obligations within the scope of ASC 410-30 (Environmental Obligations) are not ECOs.
- A voluntary initiative or statement of intent does not create an ECO liability.
The IRA Tax Credit Exclusion: A Critical Distinction
This is the scoping mistake practitioners are most likely to make. IRA renewable energy tax credits, including investment tax credits (ITCs) and production tax credits (PTCs), are explicitly excluded from Topic 818. The exclusion applies regardless of whether the entity has a current tax liability or intends to use the credit.
As EY notes: "Because income tax credits are excluded from the definition of an environmental credit, entities should continue to account for renewable energy tax credits, including those associated with the Inflation Reduction Act, in accordance with other US GAAP."
RECs and ITCs are not the same instrument. A REC certifies that one megawatt-hour of electricity was generated from a renewable source and is separately transferable. An ITC is a tax credit that reduces an entity's income tax liability. Only the REC falls under Topic 818.
The Capitalize-vs-Expense Decision: How the Recognition Model Works
The core of ASU 2026-02 is a use-intent-based recognition model. Whether a credit hits the balance sheet or the income statement depends on what the entity probably intends to do with it.
An environmental credit is recognized as an asset if it is probable, collectively, that the entity will:
- Use it to settle an ECO (compliance use)
- Transfer it in an exchange transaction (sale or trade)
- Use it in a nonreciprocal transfer (e.g., a grant to another party)
If none of those conditions are met, the cost is expensed immediately. This includes credits purchased for voluntary purposes, such as carbon-neutral or net-zero initiatives.
Key takeaway: A carbon offset bought to meet a cap-and-trade compliance obligation is capitalized. The same offset bought to support a voluntary net-zero pledge is expensed the day you acquire it.
This distinction creates an operational challenge: teams must document intended use at the point of acquisition and reassess it at each reporting date. A change in intent can trigger reclassification.
Reassessment runs one way for assets. If it stops being probable that a credit will settle an ECO, be exchanged or be used in a nonreciprocal transfer, you derecognize it through earnings (ASC 818-20-40-2). A credit you derecognized, or never recognized, can't come back onto the balance sheet later (ASC 818-20-40-3).
Voluntary Carbon Credits
Most voluntary carbon credits hit expense when you incur the cost. A net-zero pledge, a carbon-neutral claim or a science-based target isn't a law, statute or ordinance, so it creates no ECO, and with no ECO there's no compliance use to anchor an asset.
Two details catch teams out. You can't park those costs in the carrying amount of another asset such as inventory, and a nonrefundable deposit toward voluntary credits is expensed too (ASC 818-20-25-1 and 25-3).
The exception is a credit you expect to sell or transfer. If that's probable, it's a noncompliance asset. Where a program has obligated parties, such as California's Low Carbon Fuel Standard, only an obligated party has an ECO, so the same credit can be a compliance asset for one company and, unless held for sale, an expense for another.
Compliance Credits vs. Noncompliance Credits
| Category | Definition | Subsequent Measurement |
|---|---|---|
| Compliance credit | Probable of being used to settle an ECO | Measured at cost; not remeasured and not tested for impairment |
| Noncompliance credit | All other credits recognized as assets (held for sale, trading, or a nonreciprocal transfer) | Measured at cost less impairment; tested at each reporting date, with a loss for any excess of carrying value over fair value and no reversals |
Entities may also make a class-wide policy election to measure eligible noncompliance credits at fair value, per Deloitte's Heads Up on the standard.
Eligible means obtained in an exchange transaction, a nonreciprocal transfer other than a regulator grant, or a business combination (ASC 818-20-35-9), so regulator-granted and internally generated credits don't qualify. Once a credit is at fair value it stays there until derecognized. Switching a class to fair value later is applied prospectively with a cumulative-effect adjustment at the start of that annual period, while picking fair value as your initial policy isn't an accounting change (ASC 818-20-35-8 and 35-10).
Costing Methods
Three methods are permitted for measuring environmental credit assets:
- First-in, first-out (FIFO)
- Average cost
- Specific identification
Entities must disclose the method elected. The choice has real P&L implications for entities with large, actively traded credit portfolios where prices fluctuate.
Apply the method separately to compliance and noncompliance credits (ASC 818-20-35-2). The funded ECO uses the same costing as the compliance credits expected to settle it (ASC 818-30-30-2), so the election flows straight into compliance expense.
In a rising market, FIFO assigns the oldest, cheapest credits to the funded ECO, so compliance expense runs lower and the credits left on hand carry newer, higher costs. Average cost blends vintages. Specific identification needs credit-level sub-ledger tracking.
How to Measure an ECO Liability: The Layered Model
ECO liabilities are recognized when obligating events occur on or before the reporting date. The measurement follows a layered model that distinguishes the funded portion (credits on hand) from the unfunded portion (credits still needed).
Recognition runs on events to date. You test whether credits would be due if the reporting date were the end of the compliance period, even when the period ends later (ASC 818-30-25-1). You don't forecast future activity that might shrink or erase the obligation (ASC 818-30-30-4 and 55-4), and under a threshold program no liability arises until emissions pass the threshold (ASC 818-30-55-3).
Holding enough credits doesn't make the liability go away. It makes the liability funded, measured at those credits' carrying amount.
Funded Portion
The funded ECO is measured at the cost basis of the compliance credits on hand that the entity intends to use to settle the obligation. Critically, the funded ECO is measured after the recognition and measurement of the environmental credit asset. This sequencing is operationally important: you must first confirm which credits you have on hand and intend to use, then link the liability measurement to those assets' carrying amounts.
Unfunded Portion
The unfunded ECO (credits still needed at period-end) is measured in layers, working through three sub-categories in order:
| Settlement Intent | Measurement Basis |
|---|---|
| Cash settlement (intent and ability to pay cash) | Cash settlement amount specified by the program |
| Firm commitment to procure credits (unconditional purchase commitment for a fixed quantity at a fixed price, or unconditional right to receive a fixed quantity under a program or contract) | Estimated cost basis of credits to be obtained, which may differ from the contract price |
| Remaining unfunded (everything else) | Fair value of credits needed to settle the ECO, per ASC 820, as of the balance sheet date |
The residual unfunded portion requiring ASC 820 fair value measurement is where audit complexity concentrates. Auditors will scrutinize the inputs, market data, and assumptions used to value credits that may trade in thin or illiquid markets.
Gross Presentation
Environmental credit assets and ECO liabilities must be presented gross on the balance sheet. Netting is not permitted. For utilities, refiners, airlines, and other entities with large compliance programs, this requirement can materially increase reported total assets and total liabilities without changing net equity. Investor communication teams should prepare for questions.
The income statement moves too. The unfunded portion is remeasured at each reporting date, so its fair value layer swings with credit prices, and ECO costs go to earnings unless another Topic puts them into an asset such as inventory (ASC 818-30-25-1 and 35-1).
Effective Dates and Early Adoption
| Entity Type | Effective For Annual Periods Beginning After | First Calendar Year-End Application |
|---|---|---|
| Public business entities (PBEs) | December 15, 2027 | Fiscal year 2028 |
| All other entities (private companies, NFPs) | December 15, 2028 | Fiscal year 2029 |
Interim periods within those annual periods are included. Early adoption is permitted for all entities, in any interim or annual period not yet issued, but it always takes effect from the beginning of that annual period (ASC 818-10-65-1(c)).
KPMG's June 2026 effective date matrix flags ASU 2026-02 as having a "complex" effective date, meaning additional analysis is required to confirm applicability for a given entity's specific facts.
One practical note: EY's effective date matrix as of March 31, 2026 does not list ASU 2026-02, because the standard was issued May 19, 2026, after that matrix's cut-off. Teams relying on that matrix alone will miss it. Use the KPMG June 2026 matrix or the FASB's ASU page directly.
Should you early adopt? The case for early adoption is strongest when:
- Your current accounting produces results that are unfavorable or inconsistent with peers.
- You are redesigning your credit tracking systems anyway (e.g., for ISSB S2 or SEC climate disclosure readiness).
- Your auditors and audit committee want more time to work through the fair value measurement of the residual unfunded ECO.
The case against is simpler: the standard is new, implementation guidance is still developing, and the transition mechanics require careful opening-balance work.
Transition: Modified Retrospective, No Restatement
There is one transition method, often called modified retrospective. The ASU applies retrospectively through a cumulative-effect adjustment to opening retained earnings as of the beginning of the annual period of adoption, and nothing before that period is recast. There's no prospective option, and full retrospective adoption isn't permitted (ASC 818-10-65-1(d); BC168).
At transition, environmental credits on hand are measured as follows:
- Compliance credits: At the entity's carrying amount at the date of initial application.
- Noncompliance credits: At the lower of carrying amount or fair value at the date of initial application.
- Internally generated or regulator-granted credits: Either per intended use (the two bullets above) or at transaction costs incurred, under an entity-wide election.
- Eligible noncompliance credits: At fair value, under a class-wide policy election.
A few more steps happen at the date of initial application:
- Voluntary credits: Derecognize their carrying amount, and any nonrefundable deposit made to obtain them, unless the cost was already capitalized into another asset such as inventory.
- Credits already inside another asset: Leave that cost in the carrying amount of the other asset.
- ECO liabilities: Recognize and measure them under Topic 818 at that date. The ASC 805 amendments apply prospectively to later business combinations.
The retained earnings adjustment will be largest for entities that previously expensed credits that would now be capitalized (or vice versa). Controllers should map their existing credit inventory to the new classification framework well before the adoption date to estimate the balance sheet impact.
What Disclosures Does ASU 2026-02 Require?
ASU 2026-02 requires annual disclosures covering, per Deloitte's Heads Up:
- How environmental credits were obtained (acquired, granted, internally generated, or received in a nonreciprocal transfer)
- Intended use of credits and the current/noncurrent split of compliance and noncompliance credits, with balance sheet line items identified
- The costing method elected (FIFO, average cost, or specific identification)
- Applicable ASC 820 fair value disclosures for any fair value measurements
- Description of activities and events creating ECO liabilities under each regulatory program
- Nature and timing of settlement provisions
- Accounting policies for ECOs
- How the unfunded ECO portion is measured
- Significant estimates and judgments
- Total expense for credits never recognized as assets or later derecognized, which captures voluntary credits, plus total impairment expense with the nature of the impaired credits and why, and the income statement line items (ASC 818-20-50-3)
- The nature and earnings effect of any change in use or intended use, as of the date it occurs (ASC 818-20-50-4)
- Current and noncurrent amounts of the funded and unfunded ECO portions, if not presented separately, with the balance sheet line items (ASC 818-30-50-2)
- Total ECO expense and its income statement line item (ASC 818-30-50-3)
- ECO costs capitalized into another asset during the period, with a description of that asset (ASC 818-30-50-4)
Each Topic 818 disclosure paragraph is written for annual reporting periods. Fair value measurements also carry the ASC 820 disclosures on Topic 820's own timing.
If you also report under ASU 2024-03, ASU 2026-02 adds three items to the expense disaggregation table in ASC 220-40-50-21: expense for credits never recognized as assets or later derecognized, impairment expense on environmental credits, and total ECO expense, each shown by relevant expense caption. They follow Topic 818's annual frequency. See Finrep's ASU 2024-03 implementation guide for the table itself.
These disclosures are substantive. Entities with multiple compliance programs across different jurisdictions (e.g., a utility subject to both federal RPS and state cap-and-trade requirements) will need program-level detail. Start drafting footnote language early.
SAB 74: What to Disclose Before Adoption
Until you adopt, SEC registrants owe a SAB Topic 11.M (SAB 74) disclosure for ASU 2026-02 unless the impact isn't expected to be material. The staff expects it in MD&A and asks you to consider it in the financial statement notes too. The staff says to consider:
- A brief description of the standard, the date adoption is required and any earlier date you plan to adopt
- The adoption methods allowed and the one you expect to use, if decided (for ASU 2026-02 there's only the cumulative-effect method)
- The expected impact on the financial statements, or a statement that it isn't known or reasonably estimable
- Other significant effects, such as technical violations of debt covenants or planned changes in business practices
Gross presentation is the item to test against covenants, since it raises reported total assets and liabilities without changing equity. As adoption nears, move from "currently evaluating" to a quantified or directional estimate.
How Topic 818 Interacts With Other Standards
- ASC 815: Environmental credits and ECOs in Topic 818 are outside the derivatives guidance (ASC 815-10-15-82B). A separate forward contract to buy or sell credits is its own instrument, so test it under ASC 815's general definition of a derivative.
- ASC 410-30: Environmental remediation obligations are not ECOs.
- ASC 825 fair value option: It can't be elected for ECO liabilities that can be settled in cash (ASC 825-10-15-5(g)), so the funded and unfunded model is the only measurement basis.
- ASC 805-50 and ASC 805: Purchased credits are initially measured at cost under the asset acquisition guidance in ASC 805-50-30-1 through 30-4. Credits obtained in a transaction measured under another Topic, such as a business combination, follow that Topic (ASC 818-20-30-2 and 30-3).
- ASC 610-20 and ASC 405-20: Credits are derecognized under ASC 610-20, or ASC 606 when sold to a customer (ASC 818-20-40-1). ECO liabilities are derecognized under ASC 405-20 when you remit the credits (ASC 818-30-40-1).
How ASU 2026-02 Intersects With ESG Reporting Frameworks
This is the gap that existing coverage almost entirely ignores. The instruments at the center of Topic 818 (carbon offsets, RECs, emission allowances) are also the instruments at the center of corporate net-zero strategies and parallel reporting frameworks.
ISSB S2 (Climate-Related Disclosures): ISSB S2 requires disclosure of Scope 1, 2, and 3 greenhouse gas emissions and the strategies used to manage climate risk. Carbon offsets and RECs used in Scope 2 and Scope 3 accounting will now carry a specific US GAAP accounting treatment. Finance and sustainability teams need to align on which credits are compliance vs. voluntary, because that classification drives both the accounting (capitalize vs. expense) and the GHG accounting (market-based vs. location-based Scope 2).
SEC Climate Disclosure Rules: To the extent SEC climate rules require disclosure of carbon credit usage and costs, the Topic 818 accounting will feed directly into those disclosures. Gross balance sheet presentation and the immediate expensing of voluntary credits will be visible in the financial statements.
Voluntary Carbon Markets: Credits purchased for voluntary net-zero purposes are expensed immediately under ASU 2026-02. This is a P&L impact that boards and investors will notice, particularly for companies with ambitious near-term offset strategies. ESG teams making commitments and finance teams booking the costs need to be in the same room.
Operational Implications: What Needs to Change Before Adoption
Work through five decisions in order, because each one feeds the next:
- Scope. Confirm which instruments meet the four-part credit definition and which obligations are ECOs. Where a project produces both RECs and tax credits, account for them separately.
- Intent classification. Sort each credit as compliance, noncompliance or voluntary, and document the basis.
- Measurement elections. Choose the costing method, decide on the fair value election by class, and decide whether to measure granted and internally generated credits at transaction costs on transition.
- ECO measurement. Map each program's funded portion, cash-settlement and committed-credit layers, and the residual measured at fair value.
- Transition. Build the opening retained earnings adjustment from the carrying amounts on hand at the date of initial application.
The standard's use-intent model is not passive. It requires active process design. Here is what most entities will need to build or redesign:
- Credit intake process: Capture intended use at the point of acquisition for every credit purchased, received, or internally generated. The capitalize-vs-expense decision is made at acquisition.
- Reassessment at each reporting date: Intent can change. A credit originally held for compliance that is now expected to be sold must be reclassified, and the measurement may change.
- Funded ECO sequencing: Period-end close procedures must sequence the asset measurement before the funded ECO liability measurement. This is a new dependency in the close calendar.
- Fair value inputs for residual unfunded ECO: Identify market data sources for ASC 820 Level 2 or Level 3 inputs for each credit type and compliance program. Auditors will ask.
- Costing method election: Make the FIFO/average cost/specific ID election before adoption and document the rationale. Changing methods later requires justification.
For companies already building out their ISSB S2 or SEC climate disclosure data infrastructure, integrating the Topic 818 credit tracking requirements into that same system is the most efficient path.
FAQ
Does ASU 2026-02 apply to us if we only buy RECs for green power claims?Yes. RECs meet the definition of an environmental credit under Topic 818. If you buy RECs for voluntary purposes (e.g., to claim 100% renewable electricity), the cost is expensed immediately under the new standard. You are in scope regardless of whether you have a regulatory compliance obligation.
Are IRA investment tax credits (ITCs) and production tax credits (PTCs) covered by ASU 2026-02?No. Income tax credits are explicitly excluded from the definition of an environmental credit. ITCs and PTCs remain subject to other US GAAP guidance (see ASC 740 and the proportional amortization method under ASC 323-740). Do not apply Topic 818 to these instruments.
When does ASU 2026-02 take effect for a calendar-year public company?For a public business entity with a December 31 fiscal year-end, the standard is effective for the fiscal year beginning January 1, 2028 (i.e., the 2028 annual report). Interim periods within that year are also covered. Early adoption is permitted.
Do we restate prior-year financials when we adopt?No. Transition is modified retrospective. You record a cumulative-effect adjustment to opening retained earnings at the date of initial application. Prior periods are not recast.
Can we choose prospective or full retrospective transition instead?No. ASU 2026-02 has a single transition method: the cumulative-effect adjustment as of the beginning of the annual period of adoption. Full retrospective adoption isn't permitted, and there's no prospective option.
What is the difference between a compliance credit and a noncompliance credit?A compliance credit is held to settle an ECO, a regulatory compliance obligation. A noncompliance credit is everything else: credits held for sale, trading, voluntary net-zero purposes, or nonreciprocal transfer. The classification drives both recognition (asset vs. expense) and subsequent measurement.
How does the gross presentation requirement affect our balance sheet?Environmental credit assets and ECO liabilities must be shown gross. You cannot net them. For entities with large compliance programs, this can materially increase reported total assets and total liabilities. The net equity impact is zero, but gross balance sheet size increases, which may affect leverage ratios and require explanation to lenders and investors.
Is ASU 2026-02 the same as the Topic 818 standard Finrep has covered previously?Yes. ASU 2026-02 is the ASU that creates Topic 818. They are the same standard.
The full ASU 2026-02 text is available from the FASB for entities that need to work through the standard directly with their auditors.