13F Filing Deadlines 2026: Every Date, Rule, and Trap Institutional Managers Must Know
If you manage $100 million or more in Section 13(f) securities, your 13F filing deadline 2026 calendar has four hard dates. Miss one, and you are not just late on a form, you are potentially in the crosshairs of an SEC exam that specifically flagged 13F compliance as a priority this year.
Here is the complete picture: exact dates, the arithmetic behind them, the Form SHO complication that almost no deadline article mentions, and the EDGAR mechanics that catch filers off guard at 5:31 p.m.
The Four Form 13F Filing Deadlines for 2026
The statutory rule is 45 calendar days after each calendar quarter-end. When that 45th day falls on a weekend or federal holiday, the deadline rolls forward to the next business day. Two of the four 2026 dates trigger that roll-forward.
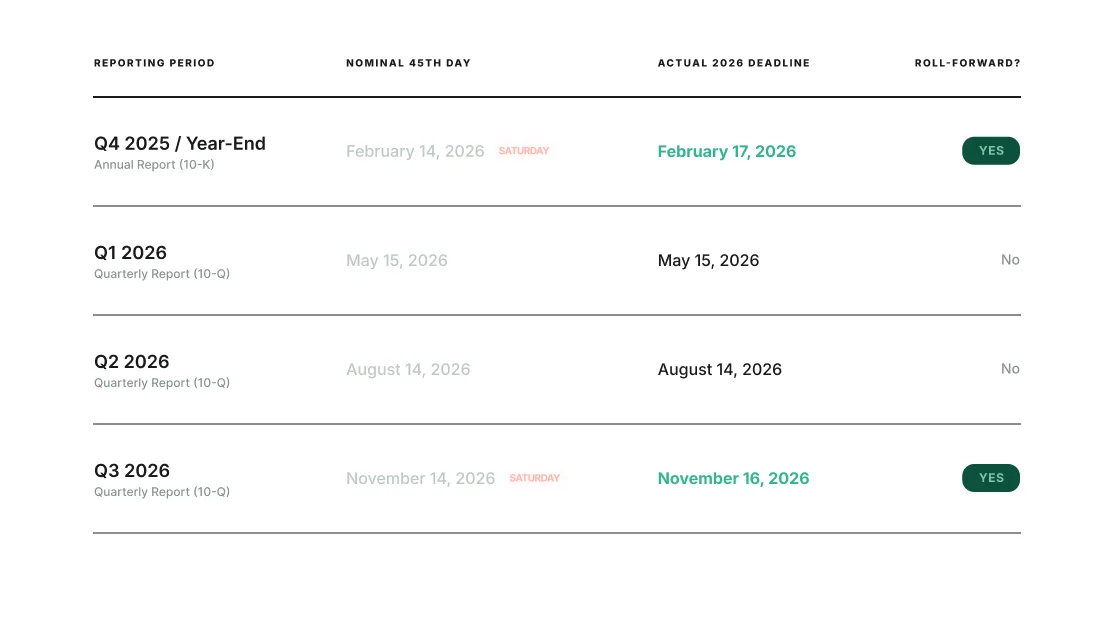
The clock comes from Rule 13f-1(a)(1), which counts 45 days from the end of the calendar year and of each of the first three quarters. Count calendar days, weekends included. Only day 45 itself moves, under Exchange Act Rule 0-3(a).
The SEC's own FAQ makes the February date explicit: "the deadline for the December 31, 2025 Form 13F report will be no later than February 14, 2026, a Saturday". Monday, February 16 was Presidents' Day, so the actual filing deadline was Tuesday, February 17. That nuance trips up more filers than you might expect.
The roll-forward changes every year, so never copy last year's dates into next year's calendar. The next two deadlines both move, and both match the deadline table in the SEC FAQ:
| Quarter-End | 45th Calendar Day | Filing Deadline | Why It Moved |
|---|---|---|---|
| December 31, 2026 (Q4 2026) | Sunday, February 14, 2027 | Tuesday, February 16, 2027 | Monday, February 15 is Presidents' Day |
| March 31, 2027 (Q1 2027) | Saturday, May 15, 2027 | Monday, May 17, 2027 | Day 45 falls on a weekend |
Key takeaway: February 17 and November 16 are the two adjusted dates for 2026, and the Q4 2026 report is due Tuesday, February 16, 2027. If your compliance calendar shows November 14 or February 14, fix it now.
Who Is Required to File Form 13F?
Any institutional investment manager exercising investment discretion over $100 million or more in Section 13(f) securities must file under Section 13(f) of the Securities Exchange Act of 1934. Three details matter here.
The $100 million threshold is not total AUM. It applies specifically to Section 13(f) securities, exchange-traded equities, certain equity options and warrants, shares of closed-end investment companies, and certain convertible debt securities. A manager with $300 million in AUM but only $90 million in Section 13(f) securities does not file. The threshold is measured by aggregate fair market value on the last trading day of any month of any calendar year.
Foreign managers are not exempt. If a non-U.S. asset manager uses any means or instrumentality of U.S. interstate commerce and exercises investment discretion over $100 million or more in Section 13(f) securities, it must file. This catches many non-U.S. managers with U.S. equity exposure who assume the obligation does not apply to them.
Governmental entities file too. Municipal pension funds, sovereign wealth funds, and other government-related entities are institutional investment managers for 13F purposes. The SEC's FAQ is explicit: "person" includes "a natural person, company, government, or political subdivision, agency, or instrumentality of a government."
First-time filers start with the December quarter. Crossing the threshold in a single month triggers a report for December 31 of that year, then reports for the first three quarters of the next year, under Rule 13f-1(a)(1).
Take a manager that first crosses $100 million on the last trading day of June 2026. It files nothing for Q2 or Q3 2026. Its first 13F covers Q4 2026, is due February 16, 2027, and the Q1 through Q3 2027 reports follow even if holdings drop back under $100 million.
Investment discretion is the trigger, not beneficial ownership. Rule 13f-1(b) borrows the Exchange Act Section 3(a)(35) definition: you have discretion if you're authorized to decide what an account buys or sells, or you make those decisions even though someone else is responsible for them. Schedules 13D and 13G run on beneficial ownership under Rule 13d-3, meaning voting or investment power over a class, so a manager can owe one filing and not the other.
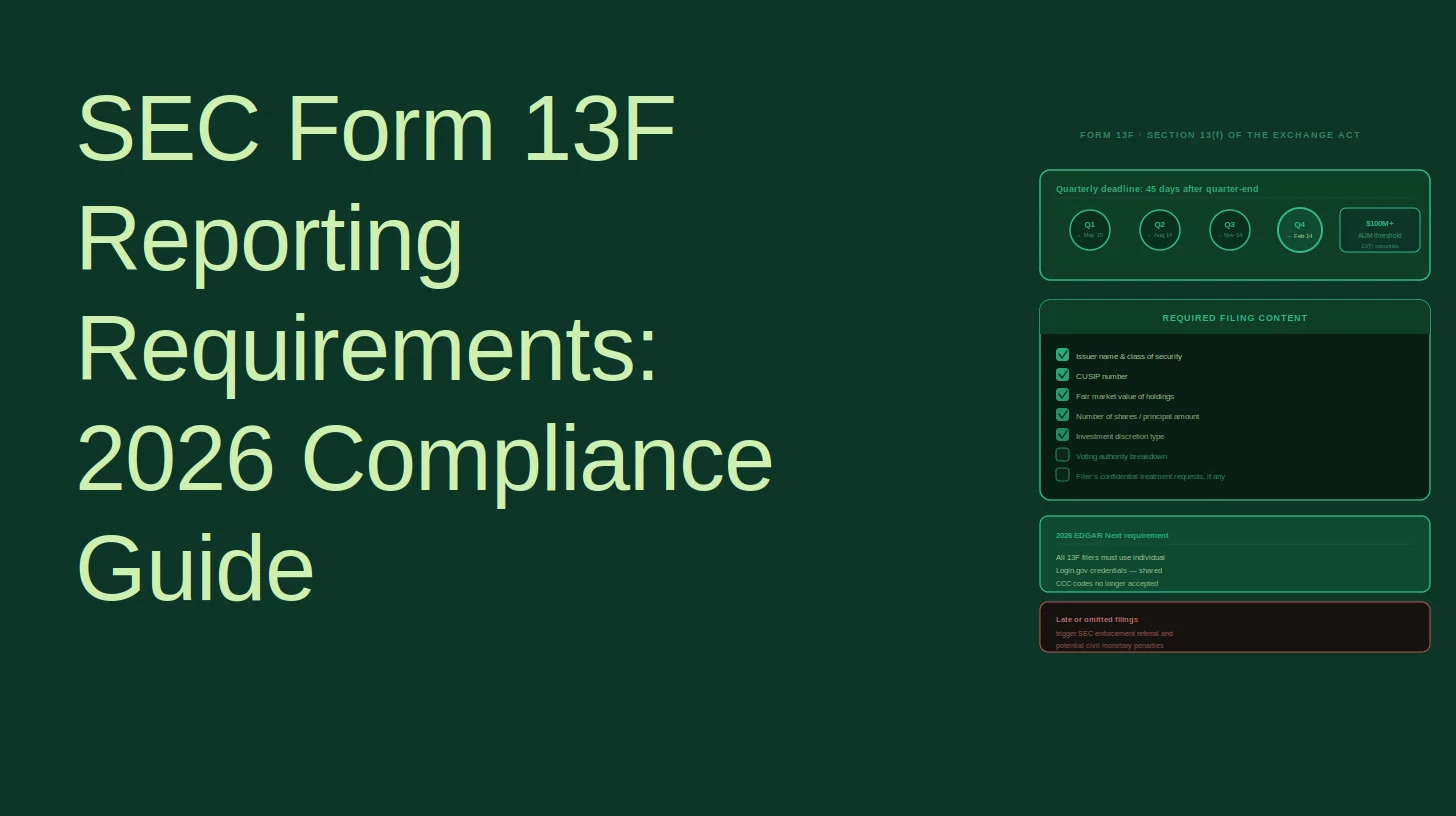
For a deeper look at the threshold mechanics and what counts as investment discretion, see Finrep's SEC Form 13F Reporting Requirements: 2026 Compliance Guide.
Was February 17, 2026 a Dual Deadline for Form 13F and Form SHO?
No, though for most of 2025 it was set to be. February 17 was scheduled as the first-ever filing deadline for Form SHO under Rule 13f-2, a separate short-sale transparency obligation that runs alongside Form 13F. That date didn't hold.
Here is the background. Rule 13f-2 was originally set to take effect January 2, 2025, with initial Form SHO filings due February 14, 2025. In February 2025, the SEC granted a temporary exemption because the technical standards for compliance were only released on December 16, 2024, immediately before the holidays, leaving insufficient time for implementation. The exemption was not a repeal. As SEC Acting Chairman Mark Uyeda stated at the time:
"This exemption gives filers more time to implement the technical updates required for compliance according to standards that were released only on Dec. 16, 2024, immediately prior to the holidays. Regardless of this exemption, abusive naked short selling as part of a manipulative scheme remains unlawful.", SEC Press Release, February 7, 2025
That order pushed the first Form SHO deadline to February 17, 2026, covering January 2026. Then, on August 25, 2025, the Fifth Circuit remanded Rule 13f-2 to the SEC, without vacating it, so the agency could weigh the rule's cumulative economic impact.
On December 3, 2025, the SEC extended the exemption to January 2, 2028. Form SHO is due within 14 calendar days after each month-end, so the first reports, for January 2028, are now due Monday, February 14, 2028.
Form SHO is distinct from Form 13F. It applies to institutional investment managers that meet or exceed certain short-position thresholds, and not all 13F filers will also be Form SHO filers. If the current timetable holds, large managers with significant short positions face two EDGAR deadlines on February 14, 2028, the same day the Q4 2027 Form 13F is due.
Key takeaway: Form SHO isn't live, and the SEC said it may propose amendments to the rule during the exemption period. If your short positions might cross the thresholds, keep counsel on scope and watch for SEC action before the January 2028 reporting period.
What Time Does EDGAR Stop Accepting Form 13F Filings on the Deadline?
EDGAR accepts filings from 6 a.m. to 10 p.m. ET on weekdays (excluding federal holidays). But there is a critical distinction buried in the rules: filings submitted after 5:30 p.m. ET receive the next business day's filing date.
This means a 13F submitted at 6:00 p.m. on August 14 is technically filed on August 17, and is late.
The exceptions to this rule are Schedules 13D and 13G, Section 16 filings, and Rule 462(b) registration statements, which receive the actual filing date regardless of time. Form 13F is not one of those exceptions.
Build your internal deadline around 5:00 p.m. ET, not 10:00 p.m. That buffer absorbs last-minute EDGAR system issues, reviewer sign-offs, and the kind of submission errors that only appear when you are rushing.
One additional note for filers watching the August 14 deadline: the SEC announced on June 1, 2026 that the June 2026 EDGAR release was cancelled. Monitor the EDGAR submissions page for any system notices ahead of the August deadline.
What Happens If You Miss a 13F Deadline?
There is no extension. The SEC FAQ says the staff doesn't grant extensions, and Form 13F has no Form 12b-25 equivalent. File as soon as possible after the deadline, and don't push out a misleading or incorrect report just to beat the clock.
Enforcement is real. On September 17, 2024, the SEC charged 11 institutional investment managers for failing to file Forms 13F. Nine paid more than $3.4 million combined, with individual penalties from $175,000 to $725,000, while two firms that self-reported and cooperated paid no civil penalty.
If EDGAR itself fails you, act the same day. Contact EDGAR Filer Support, document the outage, and ask for a filing date adjustment under Rule 13(b) of Regulation S-T, which covers good-faith filings delayed by technical problems beyond your control. Relief is discretionary, so the request needs a clean record.
What Other SEC Filings Are Due on the Same Date as Form 13F?
Form 13F does not exist in isolation. Compliance teams managing institutional portfolios face multiple overlapping obligations on the same four dates.
| Deadline | Form 13F | Schedule 13G | Form 13H (Annual) |
|---|---|---|---|
| February 17, 2026 | Q4 2025 / Year-End | Quarter-end assessment | Annual update (calendar year 2025) |
| May 15, 2026 | Q1 2026 | Quarter-end assessment | N/A |
| August 14, 2026 | Q2 2026 | Quarter-end assessment | N/A |
| November 16, 2026 | Q3 2026 | Quarter-end assessment | N/A |
| February 16, 2027 | Q4 2026 / Year-End | Quarter-end assessment | Annual update (calendar year 2026) |
Sources: Day Pitney 2026 Compliance Calendar; Skadden 2026 Filing Deadlines.
Schedule 13G quarterly assessments align exactly with the 13F dates following amendments effective September 30, 2024. Large traders filing Form 13H face their annual update on February 17 as well. If your team manages all three obligations, February 17 is the most demanding day on your compliance calendar.
You're a large trader under Rule 13h-1 if your transactions in NMS securities reach 2 million shares or $20 million in a calendar day, or 20 million shares or $200 million in a calendar month. The annual update runs on the same 45-days-after-year-end clock, and an amended 13H is due promptly after any quarter in which the information became inaccurate.
Form N-PX belongs on the same calendar. Under Rule 14Ad-1, every manager required to file Form 13F must file Form N-PX by August 31 each year, reporting say-on-pay votes for the 12 months ended June 30 on securities where it exercised voting power. New filers get a pass for the 12-month period ending June 30 of the year their first 13F is due.
One more wrinkle for Schedule 13G filers: the SEC withdrew its prior guidance in early 2025 (CDI 103.11 and 103.12) that engagement on ESG or governance topics unrelated to control would typically not affect 13G eligibility. Under the current guidance, shareholder engagement that "exerts pressure on management to implement specific measures or changes to a policy may be influencing control over the issuer" and could require a switch to Schedule 13D. Activist-adjacent managers who file both 13F and 13G should review their engagement practices against this updated standard.
Form 13F Amendments Still in Effect: Are You Using the Right Form?
The June 2022 amendments to Form 13F (SEC Release No. 34-95148) took effect January 3, 2023. If your EDGAR workflow predates that update, you may be filing an outdated form. The four substantive changes that remain in force are:
- CT checkbox on the Summary Page, a checkbox indicating when confidential treatment is being requested.
- Additional manager identifiers, CRD number and SEC file number must be reported if applicable.
- FIGI identifiers, managers may now report a Financial Instrument Global Identifier alongside (not instead of) the CUSIP number.
- Dollar rounding simplified, values must be rounded to the nearest dollar, not the nearest $1,000.
Confidential treatment requests must also be filed electronically on EDGAR as of February 28, 2023. Paper CT requests are no longer accepted. If your workflow still routes CT requests through paper, that is a compliance failure waiting to happen.
The current OMB approval for Form 13F (OMB Number 3235-0006) expires January 31, 2029, which signals no near-term structural overhaul of the form is coming. What you see now is what you will be filing through at least 2028.
The Quarterly 13F List: Check It Before You File
Section 13(f) securities are defined by reference to the SEC's official quarterly list. The Q1 2026 list was published March 31, 2026. Filers may rely on the current list when determining which holdings to report for a given quarter.
This matters in practice. Securities are added and removed from the list quarterly. A holding that was reportable in Q4 2025 may not appear on the Q1 2026 list, and vice versa. Filing without checking the current list risks both omissions and over-reporting.
Once holdings are mapped, apply the small-holding exception. Special Instruction 9 lets you omit a position only if you hold fewer than 10,000 shares (or under $200,000 principal amount of convertible debt) and it's worth less than $200,000. Both tests must pass: the SEC FAQ says 9,800 shares worth $205,000 must be listed, and so must 10,500 shares worth $198,000.
Shared Investment Discretion: The Sub-Adviser Trap
Where two or more managers each required to file Form 13F exercise investment discretion over the same securities, only one manager must include those securities in its report. The other manager must identify the reporting manager in its own filing. This anti-duplication rule is set out in Special Instructions 5 and 7 of the Form 13F General Instructions.
Sub-advisers and wrap-fee program sponsors frequently get this wrong. If you share discretion with another manager, confirm in writing which entity is the reporting manager before each filing deadline.
Every Information Table line also carries a discretion code under Special Instruction 11.b.vi. SOLE means you alone exercised discretion. DFND (shared-defined) covers sharing within set relationships, such as a bank holding company and its subsidiaries, an adviser and the funds it advises, or an insurer and its separate accounts, and OTR (shared-other) covers every other arrangement.
A Back-Schedule That Beats the 5:30 p.m. Cut-Off
Day 45 is the outer limit, not your target. Work backward from it each quarter:
- Day 0 (quarter-end): Lock positions and values at the close of the last trading day of the quarter.
- Days 1 to 10: Pull the 13F List for the quarter, map every holding to it, apply the small-holding exception, and confirm in writing which manager reports any shared positions.
- Days 11 to 25: Build the Information Table in EDGAR XML. Values go to the nearest dollar, every line needs a CUSIP (FIGI is optional), and the cover page needs your CRD and SEC file numbers.
- Days 26 to 35: Run compliance review. Decide on any confidential treatment request, prepare it for electronic filing, and check the Summary Page box.
- Days 36 to 40: Validate the XML, check EDGAR notices for maintenance windows, and test EDGAR credentials for your primary filer and a named backup.
- Day 40, by 5:00 p.m. ET: Submit and keep the acceptance notice showing the filing date. A bank with FDIC-insured deposits also sends a copy to its bank regulator, as Section 13(f)(5) requires.
2024 13F Deadlines and How to Prove a Past Filing Was Timely
Exam prep often means showing that earlier filings were on time. All four 2024 deadlines fell on weekdays, so none rolled forward:
| Quarter Reported | Quarter-End | Deadline |
|---|---|---|
| Q4 2023 | December 31, 2023 | Wednesday, February 14, 2024 |
| Q1 2024 | March 31, 2024 | Wednesday, May 15, 2024 |
| Q2 2024 | June 30, 2024 | Wednesday, August 14, 2024 |
| Q3 2024 | September 30, 2024 | Thursday, November 14, 2024 |
To check a past filing, pull the manager's 13F-HR filings on EDGAR by CIK and compare each filing date with the deadline. The EDGAR filing date already reflects the 5:30 p.m. rule, so any date after the deadline means the report was late. Then confirm the filing used the amended form in force since January 3, 2023, and that any confidential treatment request went in electronically.
SEC Exam Priority: 13F Is Not Just a Calendar Exercise in 2026
The SEC's Division of Exams released its FY 2026 Examination Priorities in November 2025. Form 13F compliance, alongside Form N-PX, is specifically flagged for investment advisers with activist strategies. Examiners are looking at whether activist managers' holdings disclosures are accurate, complete, and consistent with their fiduciary obligations.
The 2026 priorities also flag increased scrutiny of advisers managing both private funds and registered investment companies with similar strategies. If your 13F holdings overlap with a registered fund's portfolio, expect examiners to test consistency.
This is not a theoretical risk. It means your 13F compliance program needs to be exam-ready, not just deadline-ready.
FAQ
What is the Form 13F deadline for Q4 2025?February 17, 2026. The nominal 45-day deadline falls on February 14, a Saturday, and Monday, February 16 is Presidents' Day, so it rolls forward to Tuesday, February 17.
When is the Form 13F for Q4 2026 due?Tuesday, February 16, 2027. The 45th day after December 31, 2026 is Sunday, February 14, and Monday, February 15 is Presidents' Day.
How delayed are 13F filings relative to the quarter they cover?Up to 45 calendar days. A Q2 2026 filing (covering April through June 30) is not due until August 14, 2026, meaning the market sees holdings data that is nearly six weeks old by the time it is public.
Does the $100 million threshold apply to total AUM or only Section 13(f) securities?Only Section 13(f) securities. Total AUM is irrelevant. The threshold is measured by aggregate fair market value of qualifying securities on the last trading day of any month of any calendar year.
Do foreign institutional investment managers have to file Form 13F?Yes, if they use any means or instrumentality of U.S. interstate commerce and exercise investment discretion over $100 million or more in Section 13(f) securities.
What is the EDGAR cut-off time for Form 13F on a deadline day?5:30 p.m. ET. A filing submitted after that time receives the next business day's date and is technically late. EDGAR accepts submissions until 10 p.m. ET, but the 5:30 p.m. cut-off is what determines the filing date for 13F purposes.
Is Form SHO the same as Form 13F?No. Form SHO is a separate monthly filing under Rule 13f-2 for managers that meet certain short-position thresholds, on a 14-day monthly cycle rather than the 45-day quarterly cycle of Form 13F. It isn't live yet: the SEC's December 2025 order moved the first filing to February 14, 2028, for January 2028.
Are 13F filings public, and how often does the SEC publish 13F data?Yes. Public 13F filings sit on EDGAR, searchable by manager, though holdings granted confidential treatment stay out while that treatment lasts. The SEC also posts quarterly 13F data sets timed to follow the February, May, August and November deadlines, and since March 2024 each set covers the prior three months.
Can I still submit a paper confidential treatment request with my 13F?No. All CT requests must be filed electronically on EDGAR. Paper requests have not been accepted since February 28, 2023.